Introduction
Purchasing a private jet represents one of the most significant investments for high-net-worth individuals and corporations. One of the most critical decisions buyers face is whether to finance a new aircraft or a pre-owned jet. The choice influences interest rates, loan structures, depreciation, and long-term operational costs.
In this comprehensive guide, we explore the differences between financing new and used private jets, provide real-world deal examples, and offer insights on how buyers can optimize their financing strategy. With a focus on current trends, lender practices, and market data, this article equips prospective owners with the knowledge to make informed decisions.
Understanding Private Jet Financing
Private jet financing allows buyers to spread the cost of an aircraft over several years instead of paying upfront. Financing options vary based on aircraft age, type, and market value. Key elements of jet financing include:
-
Loan type: Term loan, operating lease, or finance lease.
-
Interest rate: Typically influenced by the aircraft’s age and residual value.
-
Down payment: Often 20–40% of the purchase price.
-
Loan term: Usually 3–10 years, depending on buyer preference and aircraft type.
Financing a new jet usually involves slightly higher costs upfront but comes with longer warranties and modern technology, whereas used jet financing offers lower acquisition costs but may carry higher maintenance risks.
Key Differences Between New and Used Jet Financing
| Feature | New Jet Financing | Used Jet Financing |
|---|---|---|
| Interest Rates | Typically lower (4–6%) due to higher collateral value and warranty coverage | Slightly higher (5–8%) due to depreciation risk and potential maintenance costs |
| Down Payment | 20–30% | 25–40% |
| Loan Terms | Longer terms possible (up to 10 years) | Shorter terms (3–7 years) preferred by lenders |
| Maintenance Costs | Lower in first 3–5 years | Higher and unpredictable depending on aircraft age |
| Depreciation | Slower, predictable | Faster, especially for older aircraft |
| Insurance | Easier to insure at standard rates | May require higher premiums depending on age and history |
| Residual Value | Higher resale potential | Dependent on market and aircraft condition |
| Financing Flexibility | More flexible options with top-tier lenders | Limited options, often requiring specialized lenders |
Factors Affecting Financing Rates
Several factors determine whether a buyer will secure favorable financing:
-
Aircraft Age and Model: Newer jets retain value longer, reducing lender risk.
-
Creditworthiness of Buyer: Strong financial profiles can access lower rates.
-
Down Payment Size: Higher equity reduces lender risk and lowers interest rates.
-
Loan Term: Longer loans may carry slightly higher interest due to extended exposure.
-
Lender Type: Banks, leasing companies, and private financiers offer differing rates based on risk appetite.
Real-World Deal Examples
Example 1: New Jet Financing
-
Aircraft: Gulfstream G280 (2025 model)
-
Purchase Price: $26 million
-
Down Payment: 25% ($6.5 million)
-
Loan Term: 7 years
-
Interest Rate: 5.2%
-
Monthly Payment: ~$279,000
-
Benefits: Full manufacturer warranty, lower maintenance costs, predictable depreciation
Example 2: Pre-Owned Jet Financing
-
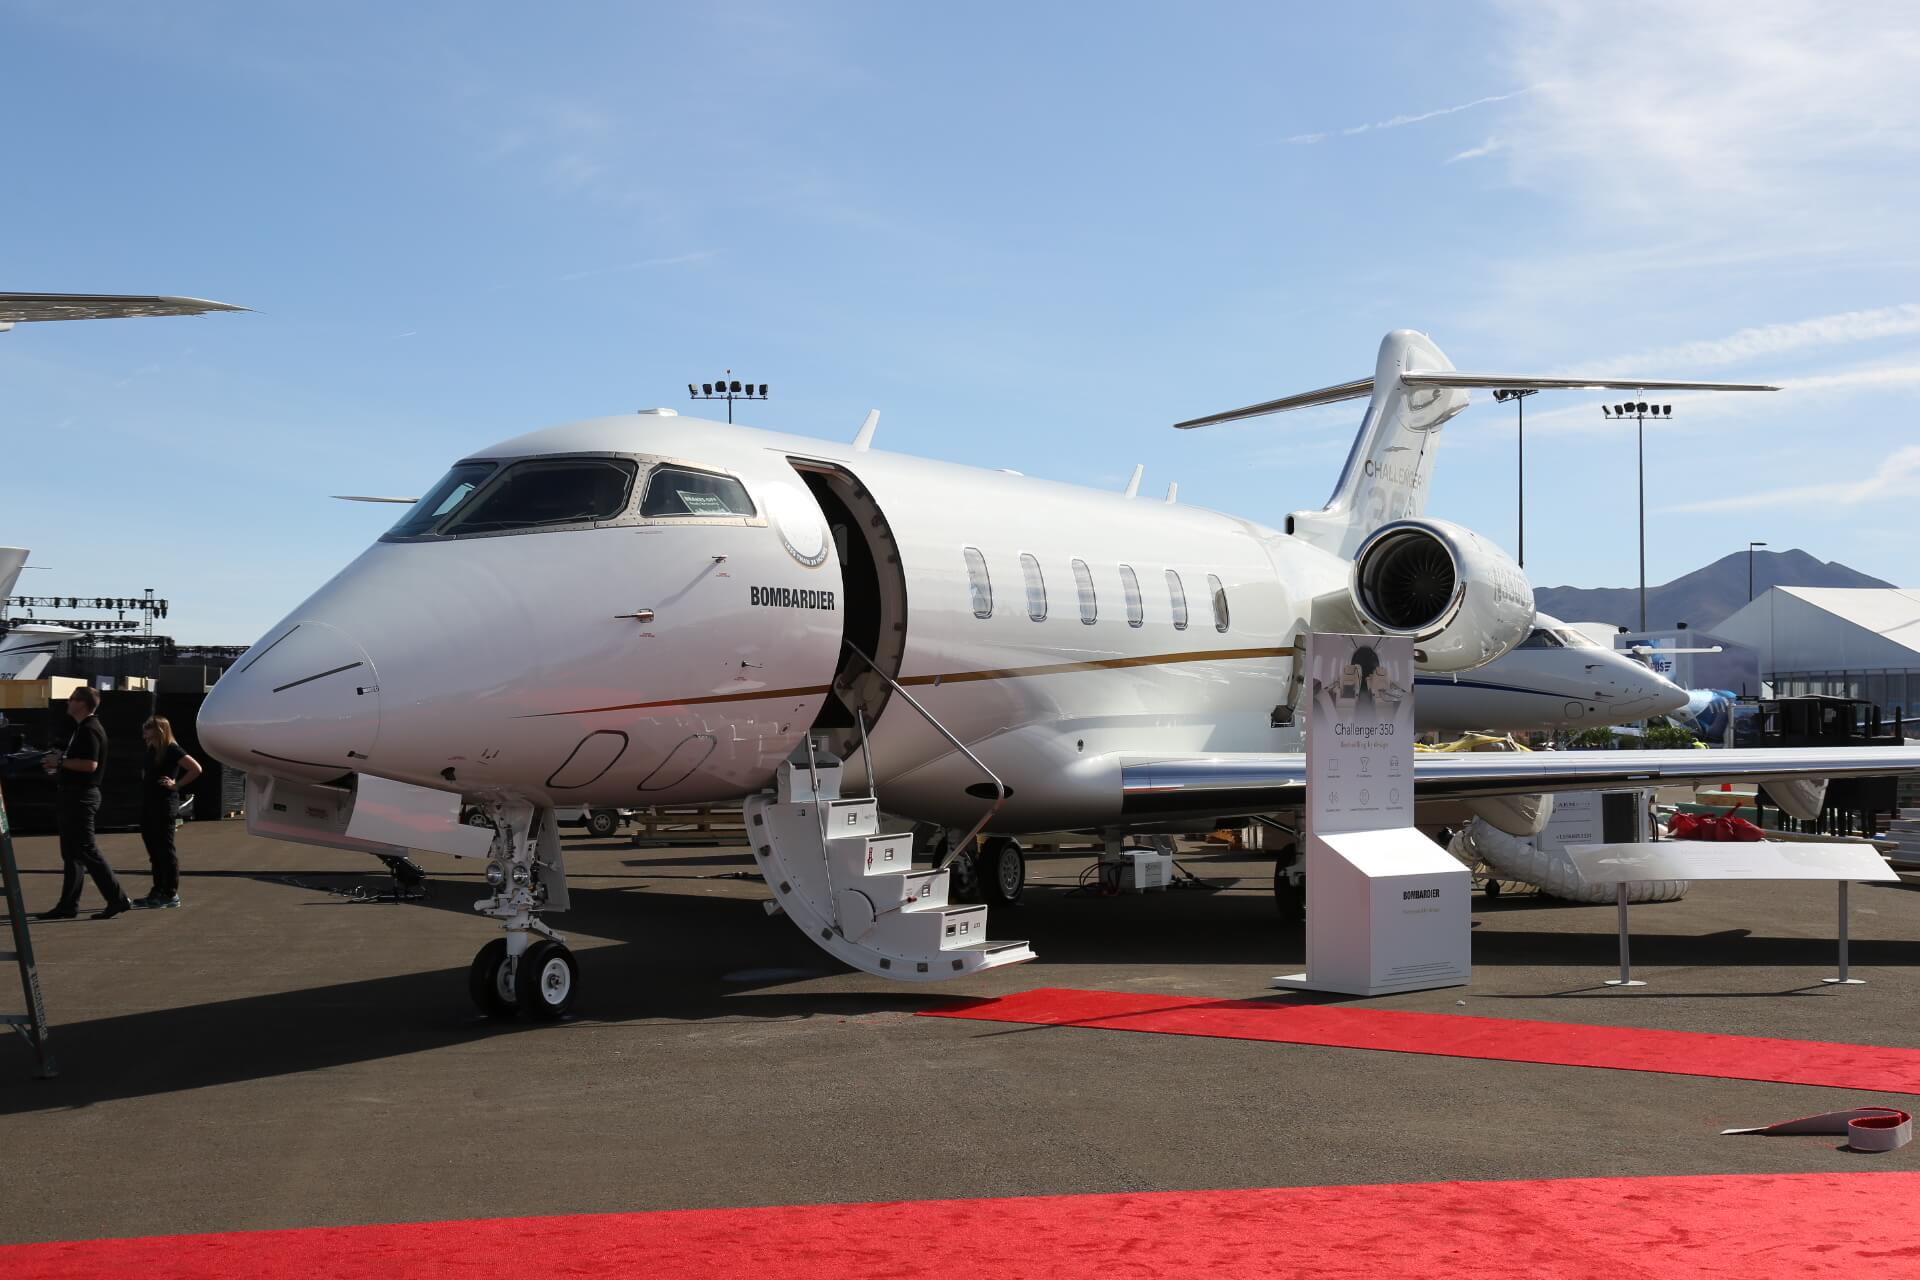
Aircraft: Bombardier Challenger 350 (2015 model)
-
Purchase Price: $13 million
-
Down Payment: 30% ($3.9 million)
-
Loan Term: 5 years
-
Interest Rate: 6.5%
-
Monthly Payment: ~$190,000
-
Considerations: Higher maintenance reserves, slightly higher interest rate, faster depreciation
These examples illustrate that while used jets require higher rates and more reserve planning, the lower upfront cost and faster availability make them attractive for budget-conscious buyers.
Financing Structures for New vs Used Jets
-
Term Loans: Straightforward loans secured against the aircraft. Interest rates are generally lower for new jets.
-
Operating Leases: Allow use of the jet without full ownership. Common for newer aircraft but sometimes extended to pre-owned jets.
-
Finance Leases: Structured like a loan but may include tax advantages. Often used for both new and used jets.
-
Bridge Financing: Short-term solutions for buyers awaiting sale of another asset. Useful for pre-owned jet acquisitions.
Advantages and Disadvantages
New Jet Financing Advantages:
-
Lower interest rates
-
Predictable maintenance costs
-
Longer lifespan and higher residual value
-
Access to the latest technology and comfort features
New Jet Financing Disadvantages:
-
Higher total cost
-
Longer delivery lead times
-
Higher insurance premiums
Used Jet Financing Advantages:
-
Lower purchase price
-
Immediate availability
-
Potentially shorter financing approval timelines
Used Jet Financing Disadvantages:
-
Higher interest rates
-
Unpredictable maintenance and repair costs
-
Faster depreciation
Tips for Optimizing Financing
-
Negotiate Interest Rates: Leverage your credit profile to get competitive rates.
-
Consider Total Cost of Ownership: Include maintenance, hangar, insurance, and crew costs.
-
Use Structured Financing: Combine term loans and operating leases to balance cash flow.
-
Evaluate Resale Potential: Consider aircraft models with high liquidity in the pre-owned market.
-
Consult Aviation Finance Experts: Specialized advisors can structure deals that optimize tax benefits and minimize risk.
Future Trends in Private Jet Financing
-
Rising Pre-Owned Market: With delivery times for new jets extending beyond 18 months, pre-owned acquisitions are gaining traction.
-
Flexible Loan Structures: Lenders are offering hybrid solutions combining leasing and term loans.
-
Green Financing: Financing programs linked to sustainable aviation fuel and eco-friendly aircraft are becoming popular.
-
Cross-Border Financing Growth: Buyers increasingly leverage international lenders to access competitive rates and tax-efficient structures.
Conclusion
Deciding between new vs used private jet financing depends on the buyer’s budget, risk appetite, and operational needs. While new jets offer lower rates, warranties, and predictable costs, pre-owned jets provide lower upfront investment and quicker access.
By understanding rate differences, loan structures, and real-world deal examples, buyers can make informed financing decisions that align with both their flying requirements and financial strategy. Partnering with experienced lenders and aviation advisors is key to securing optimal terms and avoiding costly pitfalls.